Same-Day Quotes & Certificates

COMMERCIAL TRUCK
INSURANCE

Primary liability, cargo, and physical damage for owner-operators and fleets in eligible markets.

FMCSA LicensedBMC-91X FilingsSame-Day COINew Ventures Welcome
Primary Auto Liability
Motor Truck Cargo
Physical Damage
General Liability
Trailer Interchange
Workers' Comp

Some of the insurance markets we work with

Berkshire Hathaway Homestate Companies
National Indemnity Company
GEICO
Lloyd's of London
Everspan Group
Berkley Small Business Solutions
Northland Insurance
Canal Insurance
Applied Underwriters
Crum & Forster
IAT Insurance Group
Carolina Casualty

Carrier availability varies by state, operation type, fleet size, and underwriting requirements.

Step 1 of 2 — Quick Info

Get Your Commercial Truck Insurance Quote

Same-day quotes and issuance.

Your information is secure and never shared. We use it only to prepare your quote.

No commitment required · Takes 2 minutes · By continuing, you consent to being contacted about your quote. Privacy Policy

Coverage Lines

Commercial Truck Insurance Coverages

Coverage built around your DOT authority, equipment, and freight.

Primary Auto Liability

FMCSA-required liability from $750K to $1M+, with BMC-91X filing for interstate authority.

Motor Truck Cargo

Protects freight in transit from $100K to $1M — required by nearly every broker and shipper contract.

Physical Damage

Comprehensive and collision for tractors and trailers against accidents, theft, fire, and weather.

General Liability

Covers loading-dock and premises exposures at shipper and consignee locations.

Non-Trucking Liability

Bobtail coverage for leased operators when off dispatch — commuting or personal use.

Trailer Interchange

Physical damage for non-owned trailers under an interchange agreement.

Workers' Compensation

State-mandated coverage for W-2 drivers, written mono-line across CA, AZ, NV, and TX.

Occupational Accident

An alternative to WC for owner-operators not subject to compulsory state statutes.

Why Us

Why TruxSurance

Same-Day Quote

Minutes online

Same-Day COI

Issued after binding

Trucking Specialists

Transportation only

Multiple Carriers

We shop the market

Dedicated Broker

Real person, fast answers

CA · AZ · NV · TX

Core operating states

Product and local operating guide

Building a complete the United States commercial truck insurance submission

Commercial trucking insurance is organized around the actual operation, authority, equipment, drivers, freight, routes, contracts, garaging, prior coverage, and loss history—not a one-size-fits-all package.

A commercial trucking submission should connect the legal entity, authority, equipment, drivers, routes, commodities, customers, contracts, prior coverage, and loss history. Those facts—not a city name alone—shape carrier appetite, available forms, limits, deductibles, filings, and pricing.

Document whether the business is an owner-operator, small fleet, expanding fleet, local delivery operation, regional carrier, long-haul carrier, contractor, or specialized hauler. Separate owned, financed, leased, and non-owned equipment and identify every use that may create a different exposure.

For a the United States operation, the application should state where vehicles are actually garaged, every state or corridor served, maximum and typical radius, annual mileage, commodities, revenue, vehicle values, driver experience, prior coverage, and loss history. If the business is new, include relevant ownership, driving, safety, and industry experience instead of leaving the underwriter to infer it.
Coverage structure

The coverage review may include primary auto liability, motor truck cargo, physical damage, truckers general liability, trailer interchange, hired and non-owned auto, non-trucking liability, workers compensation, occupational accident, or excess liability. Only the issued policy and endorsements determine coverage.

Deductibles, sublimits, scheduled equipment, covered causes of loss, exclusions, territory, and valuation provisions should be reviewed alongside the premium. A lower indication is not equivalent if it removes a required form or leaves a material exposure uninsured.

Contracts, filings and certificates

Customer, broker, shipper, platform, lease, and authority requirements should be compared with the proposed policy before binding. A certificate summarizes insurance; it does not create coverage or override exclusions, limits, endorsements, or contract language.

Provide the current written requirement rather than a summary from memory. Review named insured, certificate holder, additional-insured wording, waiver requests, primary and noncontributory language, notice provisions, filings, and effective dates before accepting work.

Claims-ready operating controls

A strong insurance file also explains how the business prevents and responds to loss. Document driver qualification, onboarding, vehicle inspections, preventive maintenance, cargo securement, dash cameras or telematics, accident reporting, post-loss testing, cargo documentation, and escalation responsibilities.

Keep schedules and operations current after binding. Adding vehicles, drivers, commodities, territories, contracts, equipment providers, or a different type of hauling can require carrier approval or a policy change. Report changes before the new exposure begins whenever possible.

Original Truxsurance editorial imagery

How the operation connects from equipment to delivery

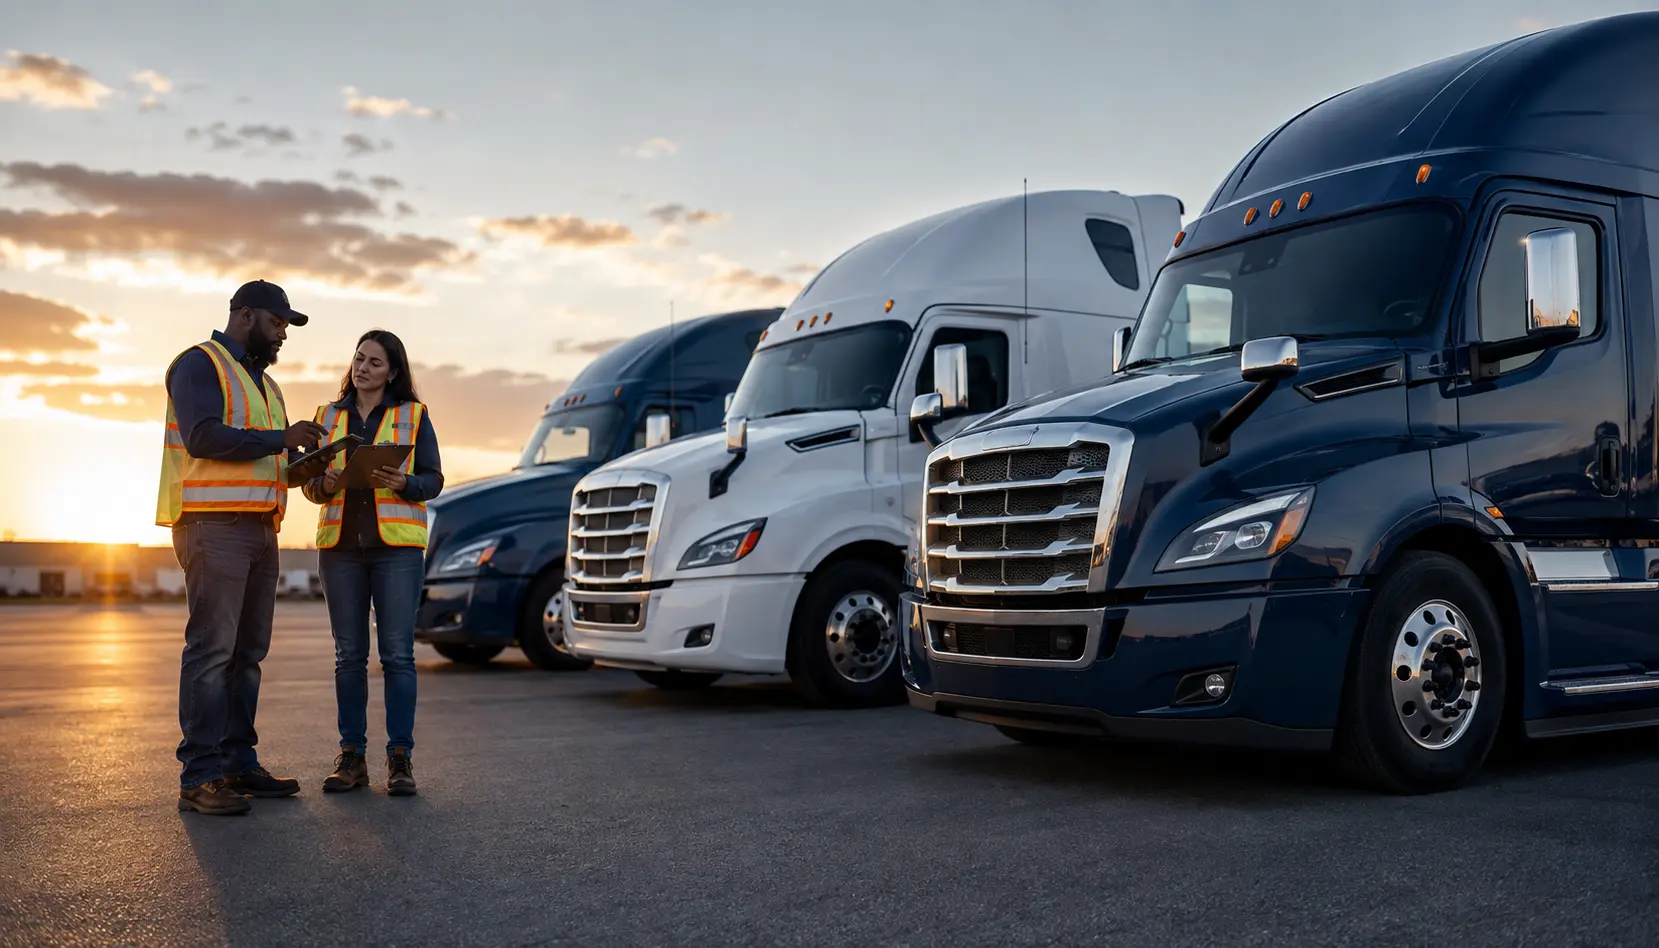
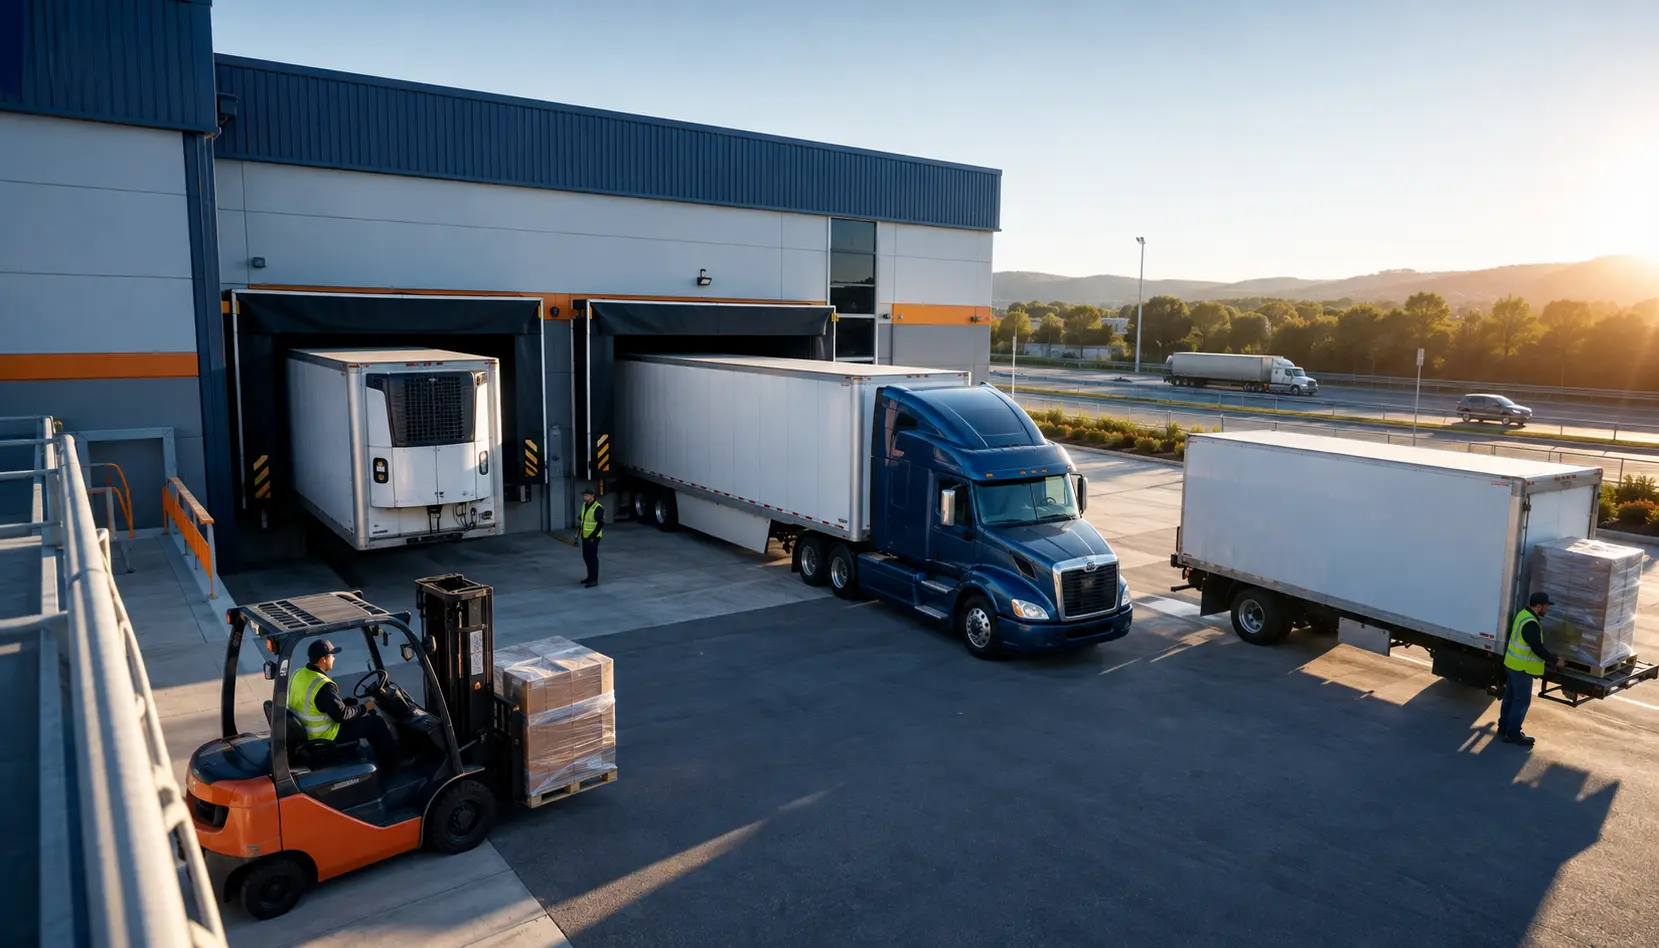
These original images illustrate the operating details an application should describe. They are representative—not photographs of a specific insured, terminal, railroad, port, or facility in the United States.

Fleet owner and safety manager inspecting commercial tractors

Fleet, driver and equipment review

A useful submission ties every scheduled unit and driver to the actual routes, cargo, garaging, safety controls and business use.

Trucks and workers handling freight at a distribution warehouse

Warehouse and delivery exposure

Cargo handling, loading, refrigeration, delivery radius, customer mix and overnight parking complete the end-to-end risk picture.

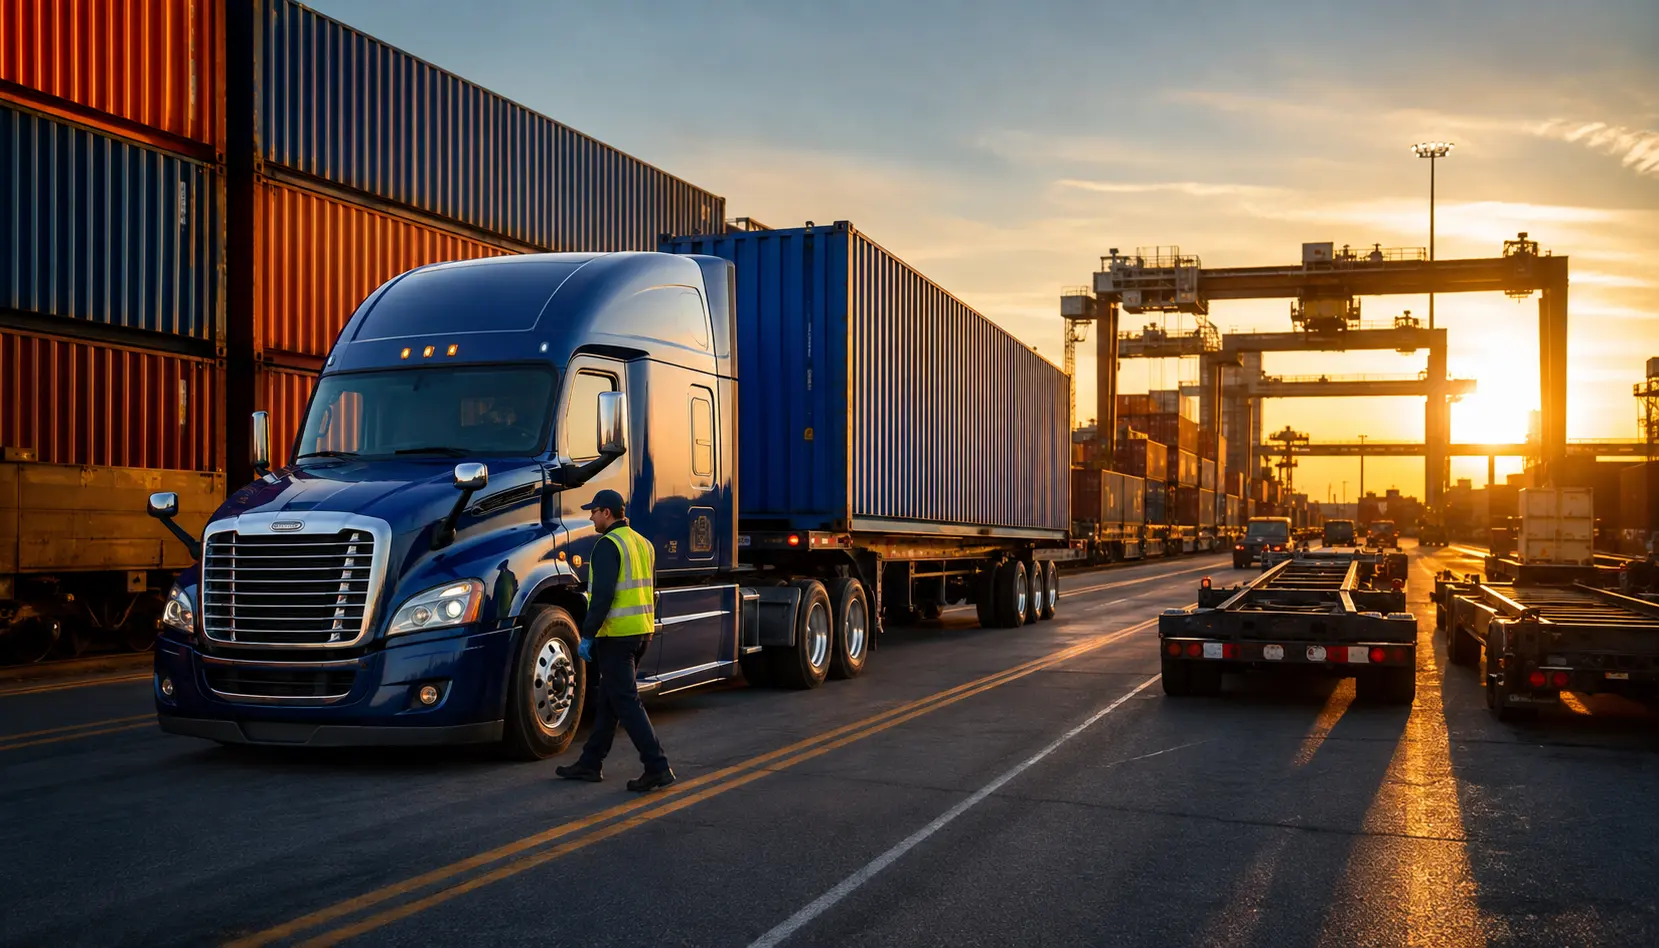
Intermodal container truck operating beside a rail ramp

Rail-ramp and intermodal operations

Rail facilities, equipment providers, container custody, chassis use and interchange requirements should be identified before quoting.

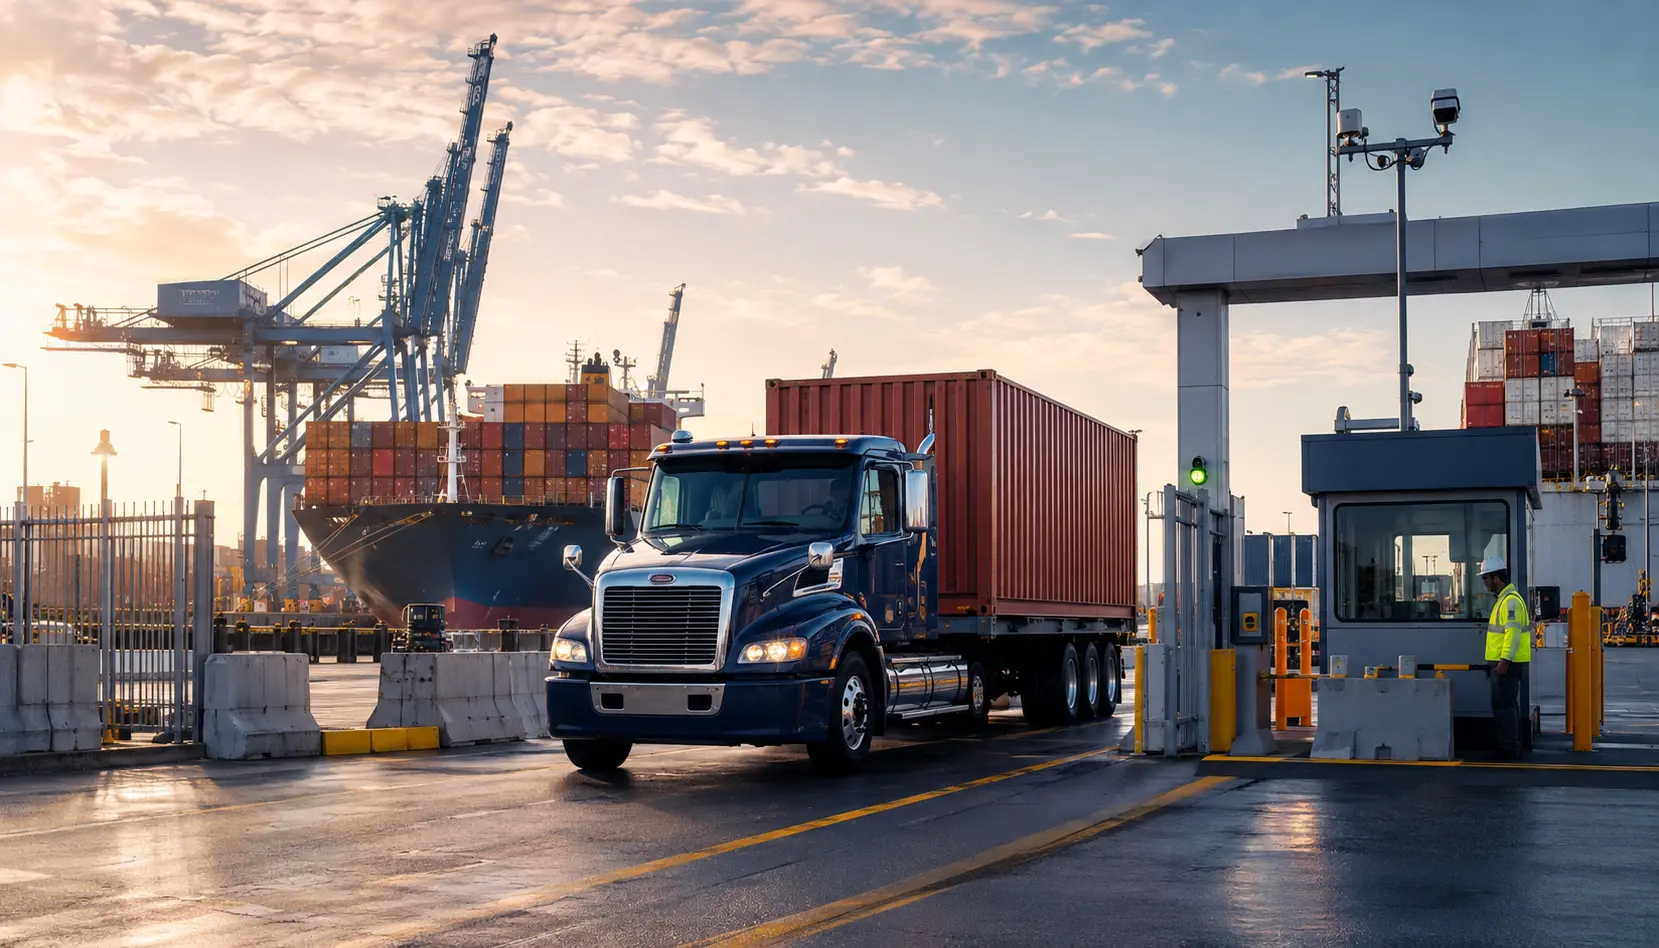
Day-cab container truck entering a marine terminal gate

Marine-terminal access

Terminal access, credentials, gate activity, appointments, container volume and contract requirements belong in the operating profile.

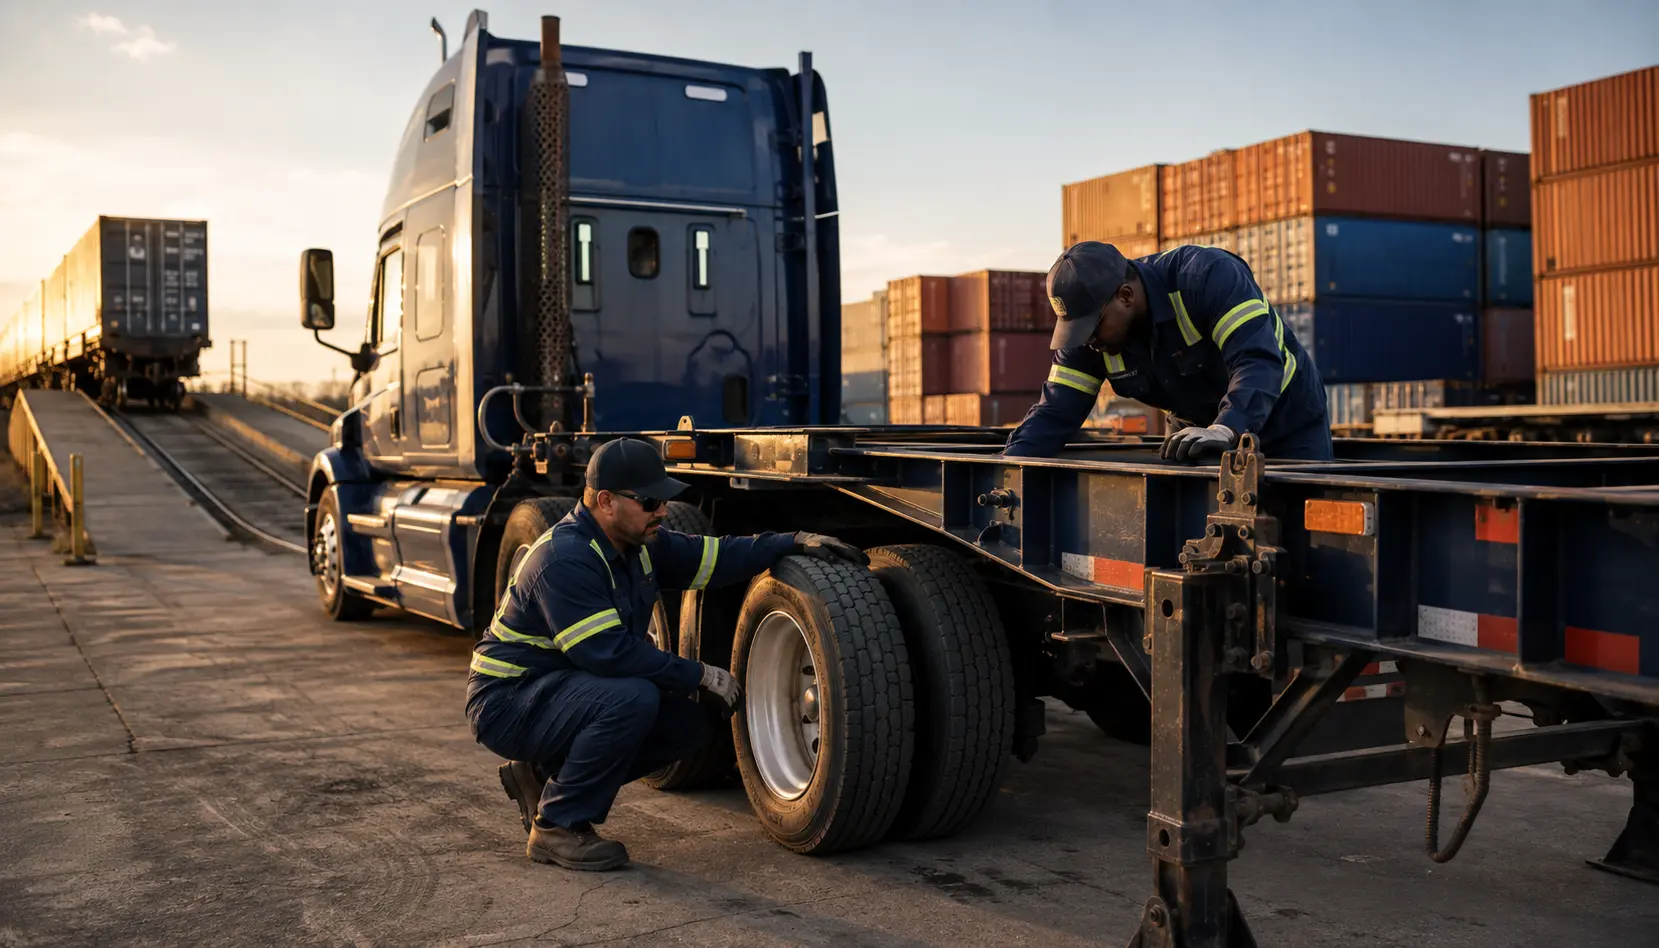
Drayage team inspecting a container chassis and tires

Chassis custody and inspection

Interchange agreements, non-owned equipment values, inspection practices, maintenance and securement affect the coverage discussion.

Quote comparison and renewal discipline

Compare proposals on the same exposure basis and verify the named insured, vehicles, drivers, limits, deductibles, forms, endorsements, filings, payment terms, exclusions, and carrier conditions. Before renewal, reconcile schedules and operations, request loss runs early, document safety improvements, and address open claims or compliance issues.

Truxsurance can help organize the insurance submission and review available market terms. Final eligibility, pricing, forms, coverage, filings, and timing remain subject to complete information, carrier underwriting, binding, and the issued policy.

Common Questions

Commercial Truck Insurance FAQ

How much does commercial truck insurance cost?

Owner-operators typically pay $8,000–$18,000 per year depending on DOT authority age, driving record, cargo type, and garaging state. New ventures run higher — often $12,000–$18,000 — because of limited loss history. Fleets are rated per unit. Submit a quote with your DOT number and equipment list for an exact figure.

What insurance is legally required to operate a commercial truck?

Interstate carriers must carry a minimum of $750,000 primary auto liability and file a BMC-91X with FMCSA. Most brokers and shippers require $1,000,000. Cargo insurance of at least $100,000 is required by nearly every load contract. If your equipment is financed, your lender will require physical damage coverage.

What is a BMC-91X filing?

The BMC-91X is a federal filing your insurer submits electronically to FMCSA to certify your liability coverage meets interstate commerce minimums. Without it, your MC authority goes inactive. Truxsurance handles BMC-91X filings same-day on every interstate policy.

Can a brand-new authority get commercial truck insurance?

Yes. We write new ventures — carriers with under two years of operating history — from day one of MC authority. Rates start higher due to limited loss history, but coverage is available immediately, structured to meet both FMCSA minimums and shipper COI requirements.

Do you write commercial truck insurance in California, Arizona, Nevada, and Texas?

Yes — these are our core markets. We specialize in carriers operating the I-10, I-15, I-40, I-5, and US-287 freight corridors that connect the Western US and Southwest, with dedicated city and state coverage pages for local agents and underwriting.

How fast can I get a certificate of insurance?

Most policies bind same-day once underwriting is complete, and your COI is issued within minutes of binding. FMCSA and BMC-91X filings go out the same day so you can start hauling without delay.

Ready for a Commercial Truck Insurance Quote?

Same-day quotes, same-day certificates, and BMC-91X filings included.